Markets
 BTC
 ETH
 BNB
 XRP
 SOL
 ZEC
 HYPE
 DOGE
 LINK
 TON
 AVAX
 SUI
 TAO
 AAVE
 PUMP
 MORPHO
 ARB
 LIT
--:-- UTC
Best crypto exchanges in Switzerland for buying in francs: bank apps and global names rated on CHF costs, oversight and custody.
Find the best exchange for
Europe
Asia Pacific
Nothing matches yet. Try a country or a region.
 By Alpha Finance Editorial Team
 Data maintained by Vince Dioquino
Every fee, register entry and clause behind a score links to the page we read it on, the Swiss one wherever a platform has it. We go back over the platforms' pages, FINMA's lists and the SRO register every quarter, and sooner when a fee, a licence or a set of terms changes.
How we score → Editorial policy Report an errorIn Switzerland you can buy crypto from your own bank. Big banks sell it inside the accounts people already use, and a few cantonal banks have followed. Outside the banks, a Swiss crypto broker only has to join a self-regulatory organisation that checks its money laundering controls. The best-known foreign exchanges serve Swiss residents from abroad, with no Swiss supervisor at all.
Cost is where Swiss buyers lose most. Many apps price Bitcoin in dollars or euros, so your francs are changed first, and some add a minimum fee per trade or a custody charge every quarter. Very few run a public order book in francs. Check before you buy whether coins can move to your own wallet, because some bank apps keep them inside the account.
All ten take Swiss residents. Of these, four are supervised here, as FINMA-licensed banks or members of a FINMA-recognised self-regulatory organisation (SRO), and four sign you up through a company licensed abroad. Another two sign you up offshore with no licence at all, which keeps their scores at 4.0 or below. Because supervision in Switzerland and the franc price of Bitcoin carry the most weight, this order won't match our worldwide ranking. The small arrows beside fees and clauses open the page each came from, and the reviews below the table give the detail.
Four platforms that come first on something a Swiss buyer weighs, each chosen on its own measured figures.
 SwissquoteFull marks for Swiss supervision.8.1 out of 10
 Bitcoin Suisse65 coins for Swiss accounts.7.0 out of 10
 BinanceA security mark of 8.0 of 10, the highest here.6.8 out of 10
 PostFinanceThe highest mark for Swiss supervision, 10.0 of 10. Level with Swissquote and Yuh on this, and ranked above all of them but Swissquote.7.4 out of 10
4 of 10 supervised in Switzerland3 are FINMA-licensed banksCHF prices read 14 Oct 2026
| # | Exchange | Score | Feestaker / maker | CHF deposits | Proof of reserveslatest published | |
|---|---|---|---|---|---|---|
| 1 | SwissquoteNot on worldwide list | 8.1 | 1% / 1% + 0.95% FXStandard I tier, on USD or EUR pairs (no CHF pairs) | Bank transfer freeCard 1.9% | None | Visit |
| 2 | PostFinanceNot on worldwide list | 7.4 | 0.95% + 0.15% a yeare-finance or the PostFinance App, from USD 0 | PostFinance accountNo other way in | None | Visit |
| 3 |  YuhNot on worldwide list | 7.1 | 1% per buy or sellYuh app; no custody fee on coins held | Bank transfer freeOnly bank transfers listed | None | Visit |
| 4 | Bitcoin SuisseNot on worldwide list | 7.0 | 0.95%, min. CHF 50Bitcoin Suisse app or Online, private clients | Bank transfer freeOnly bank transfers listed | None | Visit |
| 5 | Binance#2 worldwide | 6.8 | 0.10% / 0.10%Spot, no CHF pair | No CHF transfersP2P only | Merkle + zk | Visit |
| 6 |  Coinbase#4 worldwide | 5.7 | Not publishedNot published for Switzerland; no BTC/CHF market | Not publishedfor Swiss accounts | Audited accountsNo per-user proof | Visit |
| 7 |  BitpandaNot on worldwide list | 5.6 | 0.99% premiumBitpanda app; Bitpanda is the counterparty | Bank transferFees not published | None | Visit |
| 8 |  SwissBorgNot on worldwide list | 5.3 | 0.99% + adjustmentSwissBorg app, every loyalty rank; a liquidity adjustment sits in the price | Bank transfer freeCard 4.5% | None | Visit |
| 9 |  Kraken#6 worldwide | 4.0 | 0.80% / 0.40%Kraken Pro BTC/CHF, Tier 1 | Bank transfer freeSWIFT CHF 0.75 | Audited Merkle | Visit |
| 10 |  OKX#1 worldwide | 4.0 | 0.10% / 0.08%Spot, no CHF pair | No CHF transfersP2P only | Merkle + zk | Visit |
Score: out of 10, from six checks weighted for someone in Switzerland paying in francs, with Swiss supervision counting most. We scale the best raw result to 9.0 and the rest in proportion, and only then apply a 4.0 ceiling to any platform whose Swiss customers sign with an unlicensed company, which is why none reaches 9.0. To see why a platform scored what it did, rest the pointer on its score. Fees: the entry-tier charge per trade, in whatever currency the platform prices Bitcoin. Changing francs into dollars or euros, quarterly custody charges and hidden markups all go into the cost check instead. No platform pays for its place. Your own situation isn't part of the score, so read the ranking as general information. Our affiliate disclosure explains how we're funded.
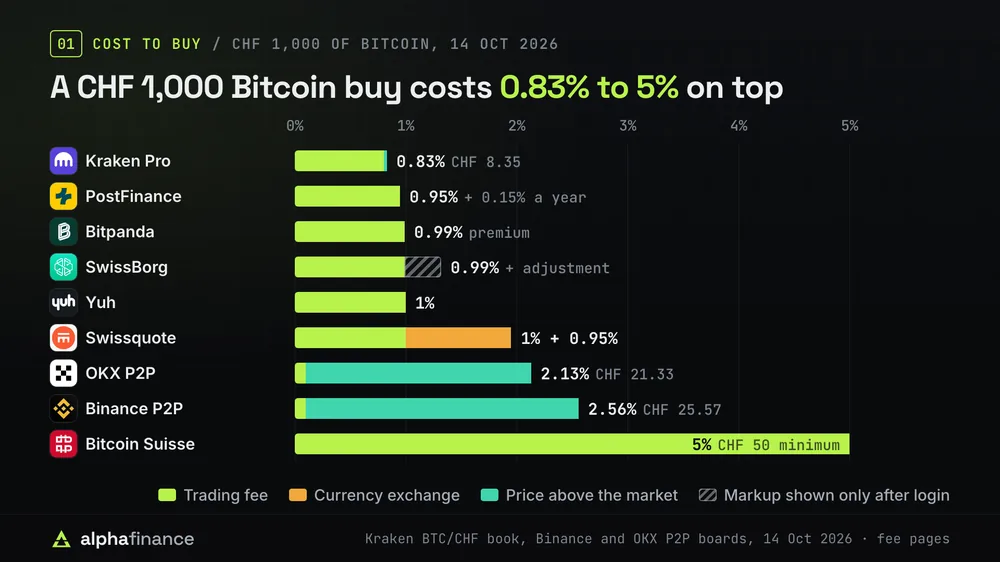
Kraken Pro was the cheapest of the three platforms with a public franc price, at CHF 8.35 over the market for CHF 1,000 of Bitcoin, and Binance P2P the dearest, at CHF 25.57. The market price is the midpoint of Kraken's book, the only public one in francs, at CHF 68,270.
Extra you pay to buy CHF 1,000 of BitcoinFee plus premium over Kraken's BTC/CHF midpoint, with Binance and OKX priced through USDT from other users
Kraken Pro0.83%CHF 8.35Order bookOKX P2P2.13%CHF 21.33P2P, then order bookBinance P2P2.56%CHF 25.57P2P, then order bookSwissquote, PostFinance, Yuh, Bitcoin Suisse, Coinbase, Bitpanda and SwissBorg show their franc price only once you're logged in, so they get no bar. Their cost check uses the steepest figure on this chart, from Binance P2P, unless their own published fee is steeper.
For the seven without a public price, the published fees are the guide. Yuh takes 1% a trade and PostFinance 0.95%, plus 0.15% a year. Swissquote charges 1% after changing your francs at 0.95%. Bitcoin Suisse charges 0.95% with a CHF 50 minimum, which makes a CHF 1,000 purchase cost 5%.
Binance and OKX have no franc market at all. You buy USDT from another user on their P2P boards, paying by bank transfer or TWINT, and the best ads were CHF 0.8515 at OKX (2.0% over Kraken's USDT/CHF) and CHF 0.8550 at Binance (2.5% over Kraken's USDT/CHF). Kraken's book also held CHF 205k of Bitcoin within 0.5% of the midpoint, and no other platform here publishes franc depth to compare.
For each platform we named the company that signs Swiss residents up, looked it up on FINMA's lists and SRO register, read its fee pages and terms, and took Bitcoin's price from its live franc book or P2P board where it has one. Each card shows the supervisor behind that company and the route a complaint takes.
Top score · Not on worldwide list
Best for buyers who want crypto inside a FINMA-licensed Swiss bank, with 55 coins and withdrawals to a wallet of their own. Francs first become dollars or euros at 0.95%, then each trade costs 1%.
Good for
Incidents in the last five years
NoneNo hacks, fines or market failures in the last five years.
Strongest regulation · Not on worldwide list
Best for PostFinance customers who want crypto in the account they already bank with, under FINMA. Prices are set in US dollars, 0.15% a year comes on top of 0.95% a trade, and coins can't leave.
Good for
Incidents in the last five years
NoneNo hacks, fines or market failures in the last five years.
Not on worldwide list
Best for app users who want a flat 1% fee from CHF 10 a buy, with Swissquote's bank behind the account. Coins can't be moved out, and its contract doesn't promise to keep them segregated if the bank fails.
Good for
Incidents in the last five years
NoneNo hacks, fines or market failures in the last five years.
Most coins · Not on worldwide list
Best for larger buyers who want a Zug crypto specialist with 65+ coins, staking and personal support. Its CHF 50 minimum fee makes small buys dear, and custody costs at least CHF 62.50 a quarter.
Good for
Incidents in the last five years
NoneNo hacks, fines or market failures in the last five years.
Best for traders who want 512 coins and the highest security mark here, through companies licensed in Abu Dhabi. It takes no francs: you buy USDT from other users on P2P, about 2.5% over the market.
Good for
Incidents in the last five years
USDe, wBETH and BNSOL lost their pegs on Binance's own order books in the 10 Oct crash; Binance paid about US$283M to users liquidated as a result.
AUSTRAC ordered an external audit of Binance Australia's anti-money-laundering controls.
Pleaded guilty in the US to anti-money-laundering and sanctions violations and agreed to pay about US$4.3B.
Best for buyers who want a US-listed exchange with audited accounts and 408 coins, through its FCA-authorised UK company. It publishes no Swiss payment methods or Swiss fee, and has no franc market.
Good for
Incidents in the last five years
A faulty update took down transfers and trading for about 50 minutes.
Fined EUR 21.5M by the Central Bank of Ireland for transaction-monitoring failures.
Bribed overseas support contractors stole personal data of 69,461 customers.
and 1 earlier
Not on worldwide list
Best for collectors who want 650+ coins, the most here, bought straight from francs at a Vienna broker licensed under MiCA. Bitpanda trades against you with a 0.99% premium on Bitcoin, and its CHF bank fees aren't published.
Good for
Not on worldwide list
Best for app users who want 400 coins and francs accepted from a Swiss-founded brand, though Swiss users sign with its French company. A 2025 breach cost its SOL strategy 97.8%, still being repaid in grants.
Good for
Best for buyers who want the cheapest Bitcoin in francs, on the only public BTC/CHF book, with free SIC deposits. Swiss users sign with a BVI company that holds no crypto licence, so the score is held to 4.0.
Good for
Incidents in the last five years
Disclosed an extortion attempt after support staff viewed limited data on about 2,000 client accounts. Kraken says there was no breach of its systems and no client funds were at risk.
Ordered by Australia's Federal Court to pay A$8M after ASIC action over its margin product.
A deposit bug let security researchers withdraw about US$3M from Kraken's own treasury, not from client accounts; the funds were returned.
and 1 earlier
Best for traders who want OKX's 437 coins, with the cheaper of the two franc P2P boards on a CHF 1,000 buy. Swiss users sign with a Seychelles company holding no licence, so the score is held to 4.0.
Good for
Incidents in the last five years
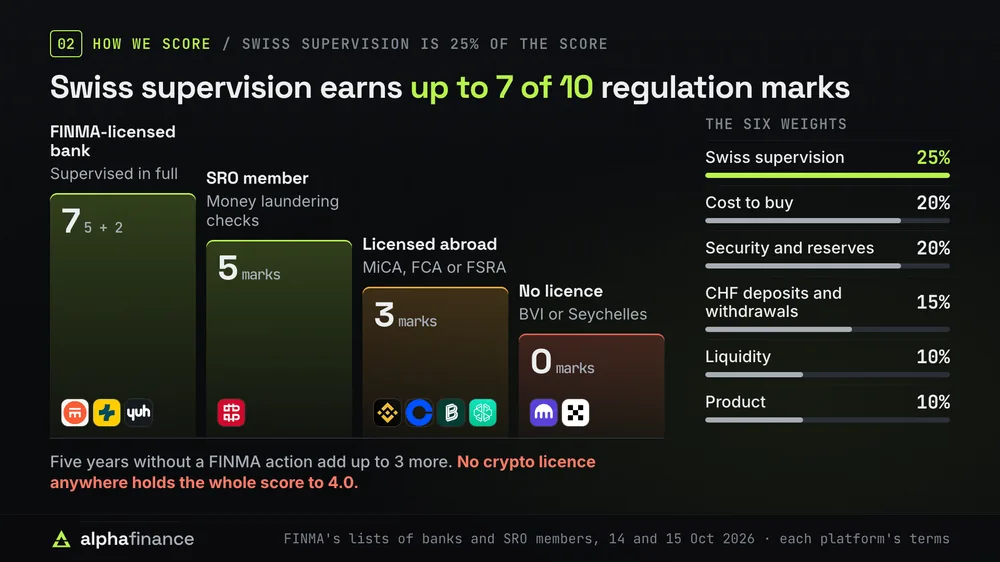
We searched FINMA's SRO register and its list of licensed banks for every company here, read the fee schedule and the terms each platform gives Swiss residents, and read every franc price in one snapshot on 14 Oct 2026. The order follows from six weighted checks, each with a fixed rule.
| Check | Weight | How it is marked |
|---|---|---|
| Cost to buy | 20% | Only Kraken shows a franc order book in public, so the midpoint of its BTC/CHF book on 14 Oct 2026 is our market price. Each platform's cheapest published way to buy CHF 1,000 of Bitcoin is priced against it, fee included. The full 10 marks go to anything within 0.2% of the midpoint, and past that 0.8 drops away for each extra 0.1%. Apps that hide their franc price until you have logged in are scored at the steepest cost measured that day, unless the fee they publish is steeper still. |
| Swiss supervision | 25% | The company you sign with earns 5 when it is a Swiss bank licensed by FINMA or a member of a FINMA-recognised self-regulatory organisation, and a bank adds 2, since FINMA supervises a bank in full and an SRO checks only money laundering rules. A crypto licence held abroad, under MiCA, from the UK's FCA or from Abu Dhabi's FSRA, earns 3 instead. A clean five-year record with FINMA adds 3, which an order or warning halves and a ruling removes. |
| Security and reserves | 20% | Marked as on our worldwide list. Up to 4 marks go to reserves: Kraken, OKX and Binance take all 4 with a proof you can search for your own balance, checked by an auditor or by zero-knowledge maths, and Coinbase through a parent's SEC-audited accounts. Lesser evidence scores lower, with 3 marks for a lookup nobody has checked or an audit limited to reserves and 2 for an attestation signed by an accountant, while the four Swiss platforms publish no proof and score 0. Binance earns 2 for a customer loss fund whose size it publishes, and Coinbase 1 for one whose size isn't given. The last 4 rest on the record since October 2021: a hack or failure that cost customers money takes 3, or 1 once all were repaid, and a data breach, a regulator's action anywhere and each market failure (2 at most) take 1 each. |
| Liquidity | 10% | Depth can only be read where a franc order book is public. On each such book in the 14 Oct 2026 snapshot we count the francs' worth of Bitcoin offered within 0.5% of the market price, and every tenfold increase adds 3.3 marks, from none at CHF 10,000 to the full 10 at CHF 10 million. The other nine show no public franc book, so their liquidity mark is 0. |
| CHF deposits and withdrawals | 15% | A free bank transfer of francs into the platform scores 4, or 1 when it costs something or no fee is published. A card, PayPal or a franc P2P board as one more way to pay in is worth 1. Buying crypto straight from francs, without changing them into dollars or euros first, adds 1. Free franc withdrawals to your bank are worth 2, and so is going two years without losing a bank or payment partner. |
| Product | 10% | Coin lists here run from 22 to over 600: 30 coins earn 1 mark, 100 earn 2 and 300 earn 3. A public BTC/CHF book is worth 2, and accounts for companies, open at seven of the ten, another 2. Staking, an OTC desk and the right to send coins to your own wallet, which not every Swiss bank app gives, are worth 1 each. |
After the marks are totalled, ceilings can cut a score. Kraken and OKX stop at 4.0 because their Swiss customers sign with companies that hold no crypto licence anywhere. No platform here meets the other two: 7.5 after a FINMA ruling or Swiss court penalty within two years, and 6.0 after a hack in the past year that customers haven't been repaid for.
FINMA's lists, the SRO register, the fee pages and the terms were all read on 15 Oct 2026. We go over them again by mid-January, or sooner if the Federal Council's crypto-institution bill reaches Parliament.
Sign-up asks for a Swiss passport, ID card or residence permit. Withdrawals go only to a bank account held in your own name, so pay in from that same account.
Only for money laundering, for now. A crypto firm must join a self-regulatory organisation (SRO) recognised by FINMA, which then checks its anti-money laundering controls. FINMA's 2025 annual report adds that crypto providers face no other specific consumer protection duties, such as warning you of the risks.
Banks are the exception. A FINMA-licensed bank that sells crypto, such as Swissquote or PostFinance, is supervised by FINMA in full, and FINMA's January 2026 guidance on crypto custody applies to it.
That is set to change. On 22 October 2025 the Federal Council opened a consultation on a new crypto-institution licence for firms that trade and hold crypto, with rules modelled on those for securities firms. The consultation closed on 6 February 2026, and no bill had gone to Parliament by October.
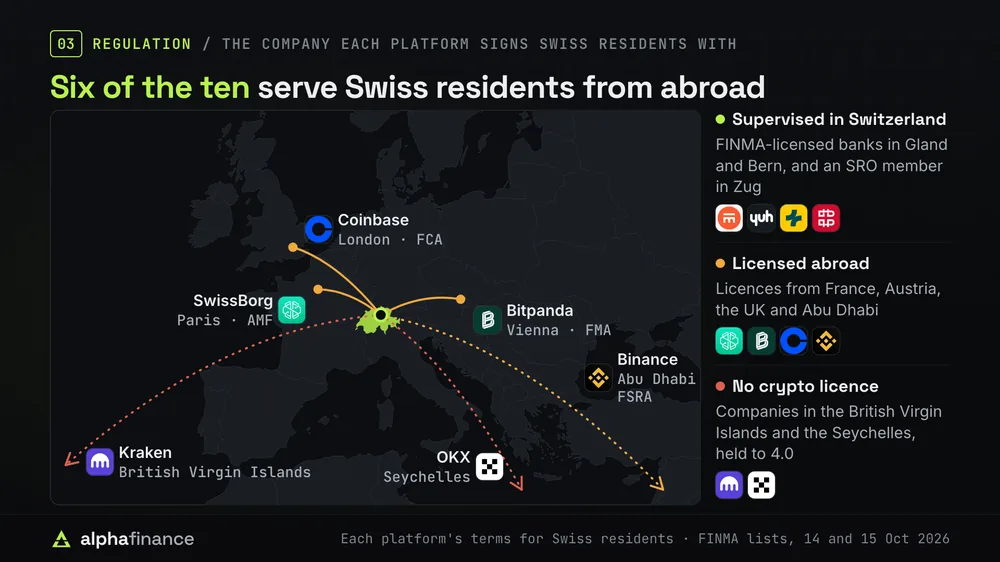
Foreign exchanges are a separate case. None of the six here has a Swiss company on FINMA's SRO register, so they serve Swiss residents from abroad. Binance, Coinbase, Bitpanda and SwissBorg rely on licences from Abu Dhabi, the UK, Austria and France. Kraken and OKX sign Swiss residents with companies in the British Virgin Islands and the Seychelles.
Write to the platform first. Banks belong to the free Swiss Banking Ombudsman, which mediates for clients of Swiss Bankers Association members, though it can't force a decision. PostFinance points unresolved complaints there, and Swissquote, an association member, is covered too.
The financial ombudsman offices that the Federal Department of Finance recognises cover financial service providers, and none of the crypto brokers or foreign exchanges here names one. Their terms send disputes to their own courts or arbitration instead: Bitcoin Suisse to Zug, SwissBorg to France, Kraken to San Francisco and Binance to Abu Dhabi.
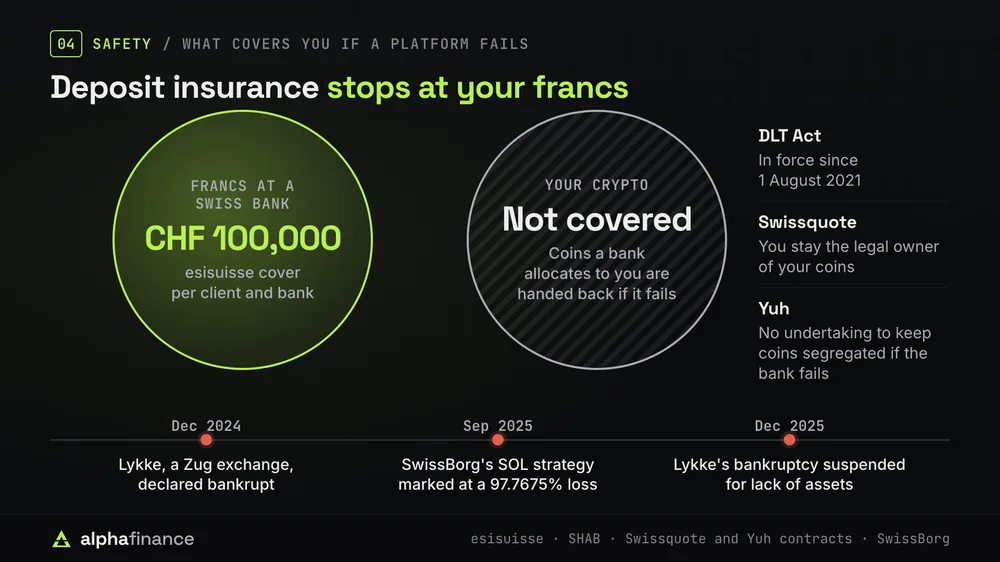
Deposit insurance doesn't cover it. esisuisse protects up to CHF 100,000 per client and bank in francs and other currencies, but not units of crypto, and not money held by a firm with a FinTech licence.
What protects your coins is the law on bankruptcy. The DLT Act, in force since 1 August 2021, set out how crypto is handled when a firm fails, and esisuisse explains that coins a bank allocates to you are handed back to you. Swissquote's contract says you remain the legal owner of your coins. Yuh's says Swissquote doesn't undertake to take every step needed for them to be segregated if the bank goes bankrupt.
Lykke is the Swiss case to know. The Zug exchange was declared bankrupt in December 2024. In December 2025 the Zug bankruptcy office suspended the proceedings for lack of assets. SwissBorg marked its SOL staking strategy at a 97.7675% loss after the September 2025 Kiln breach and is repaying users in grants.
If the platform itself loses your coins, its contract sets how much you can claim back.
| Platform | What its terms say |
|---|---|
| Swissquote | You stay the legal owner. It isn't liable if a sub-custodian goes bankrupt. |
| Yuh | No undertaking to keep your coins segregated if the bank fails. |
| Binance | Coins held on trust. No lending them without your consent. |
| SwissBorg | A custody loss is capped at the coins' market value in euros. |
| Kraken | Liability capped at US$100, and it may invest your francs and keep the interest. |
No Swiss platform here publishes a reserve proof, the record that would show customers' coins are all there. Binance, Kraken and OKX publish proofs you can search for your own balance, and Coinbase's parent has its accounts audited for the SEC.
Not investment advice
This page is general information. Nothing on it is a recommendation to buy, sell or trade any crypto asset or to use any platform. Crypto prices can fall sharply. See our affiliate disclosure for how the site is funded.
Francs move fast in Switzerland. Since 20 August 2024 banks covering more than 95% of customer payments have taken instant payments, and the rest must join by the end of 2026. Kraken credits SIC transfers in real time during banking hours.
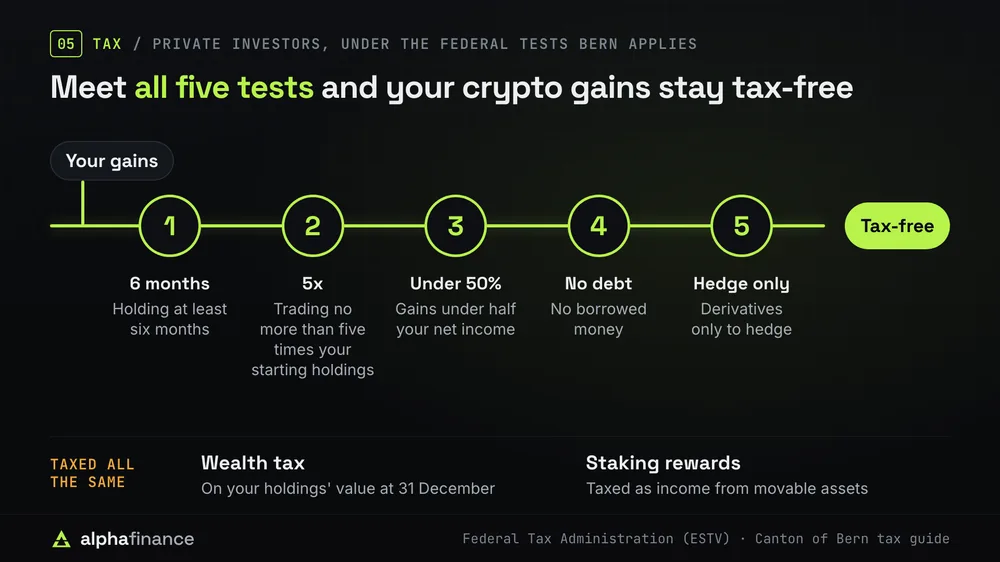
Most Swiss residents pay no tax on crypto gains. The Federal Tax Administration treats Bitcoin like a foreign currency, so a private investor's profits are tax-free capital gains and losses can't be deducted.
Two taxes do apply. Your holdings count toward cantonal wealth tax at their value on 31 December, using the rate the tax administration publishes in its Kursliste for common coins. Staking through a pool adds taxable income, which the tax administration counts as income from movable assets at the rewards' franc value on arrival.
Trade too much and you can be treated as a professional. The cantons apply the federal tests for securities traders by analogy, and Bern's tax guide lists five you must all meet to stay private: holding for at least six months, trading no more than five times your starting holdings, gains under half your net income, no borrowed money and derivatives only to hedge.
Swiss platforms will report your holdings to other countries' tax offices too, but not yet. Parliament has approved the legal basis, but the list of partner countries is still being debated, and the State Secretariat for International Finance says it can't start before 1 January 2027.
Crypto ETPs let you own crypto in a normal securities account. SIX Swiss Exchange listed 214 crypto ETPs at the end of 2025, out of 266 ETPs in all.
You buy an ETP like a share, through your bank or broker, so its custody and trading fees apply in place of a crypto platform's, and you never handle a wallet or a recovery phrase.
A wallet whose keys only you hold is out of reach if a platform fails. Not every Swiss app lets them out: PostFinance's product sheet lists sending and receiving as not currently available, and Yuh doesn't move crypto to or from other institutions.
Where withdrawals are allowed, expect proof that the wallet is yours. FINMA has required since 2019 that supervised firms send crypto only to external wallets belonging to their own customers, with no exception for unregulated wallets. Swissquote asks you to whitelist the address first and charges USD 10 to send Bitcoin, and Bitcoin Suisse charges CHF 40.
Online fraud is the cybercrime Swiss police record most. Of 36,572 victims of cyber economic crime recorded in 2025, 81.2% fell to online fraud. FINMA added over 300 names to its warning list in 2025, a record high.
Victims should alert their bank the same day, file a complaint with the cantonal police and save every message and transaction ID.
Swissquote tops our Swiss ranking at 8.1 out of 10: a FINMA-licensed bank where francs move in and out free. For other needs, Bitcoin Suisse lists the most coins, Binance scores best on security and PostFinance shares the top regulation mark.
In our snapshot it was Kraken Pro, with a public BTC/CHF book and free SIC deposits, though its Swiss company holds no crypto licence. The Swiss apps charge 0.95% to 1% a trade before any currency exchange.
For money laundering, yes: crypto firms must join a FINMA-recognised self-regulatory organisation, and banks that sell crypto are supervised by FINMA in full. A dedicated crypto-institution licence went out for consultation in October 2025 and isn't law yet.
Not on gains, if you invest privately. You declare your coins for cantonal wealth tax at their 31 December value, and staking rewards count as income. Trading often or with borrowed money can make you a professional trader, whose gains are taxed.
No. Kraken signs Swiss residents with Payward Trading Ltd in the British Virgin Islands, which isn't a member of any Swiss SRO. It has the cheapest franc book here, but its terms cap its liability at US$100 and send disputes to arbitration in San Francisco.
Both are Swiss and members of the VQF, but they sell only Bitcoin, and this page ranks platforms for buying a range of coins. Zürcher Kantonalbank sells four coins and lets none in or out, and radicant, another bank app, has closed its accounts.